As at the year 2025 Zimbabwe’s digital payments ecosystem is one of the most mobile-money-driven markets in Africa. While traditional banks remain important for large-value transactions, mobile wallets and fintech platforms dominate everyday payments, merchant transactions, remittances and peer-to-peer transfers.
Estimated Ecosystem Value
Estimated annual digital payments volume: US$15–25 billion
* Mobile money remains the dominant payment channel.
* Merchant payments continue expanding rapidly.
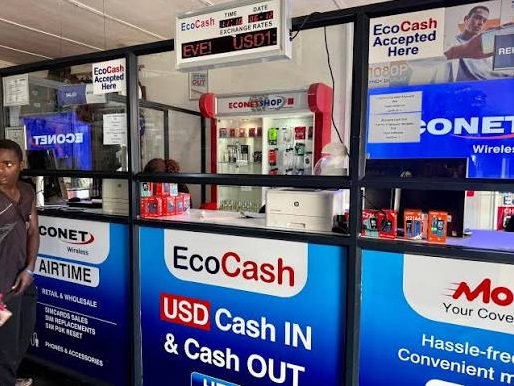
EcoCash remains the clear market leader. Recent industry reports indicate that EcoCash accounts for over 70% of national payment transactions and more than 86% of Zimbabwe’s mobile money market.
# 1. EcoCash
Parent Company: EcoCash Holdings
Estimated Share: 70%–86%
Position
EcoCash is Zimbabwe’s dominant digital payments platform and remains deeply integrated into daily commerce.
Key Services
* Person-to-person transfers
* Merchant payments
* Utility payments
* School fees
* Diaspora remittances
* EcoCash Mastercard
* Foreign currency services
Why It Leads
* Largest agent network
* Strong merchant acceptance
* First-mover advantage
* Broadest service ecosystem
EcoCash has maintained leadership despite increasing competition from newer fintech entrants.
# 2. Innbucks
Parent Company: Innbucks
Estimated Share: 5%–12%**
Position
Innbucks is currently the fastest-growing challenger to EcoCash.
Strengths
* Fast wallet onboarding
* Strong retail network through Simbisa Brands
* Popular among younger users
* Competitive transaction fees
Many analysts consider Innbucks the strongest competitive threat EcoCash has faced in years.
# 3. OneMoney
Parent Company: NetOne
Estimated Share: 5%–8%
Historically OneMoney achieved double-digit market share and remains Zimbabwe’s second-largest mobile operator-backed wallet. More recent reports suggest it processes around 7% of mobile money market activity.
Strengths
* Government-linked ecosystem
* NetOne subscriber base
* Rural coverage
# 4. Mukuru Wallet
Parent Company: Mukuru
Estimated Share: 2%–5%
Strengths
* Cross-border remittances
* Large diaspora customer base
* Southern Africa footprint
Mukuru is leveraging its remittance leadership to build a broader digital payments ecosystem.
# 5. O’Mari
Parent Company: Old Mutual Zimbabwe
Estimated Share: 1%–3%
Strengths
* Backed by a major financial institution
* Integration with insurance and investment products
* Growing digital wallet offering
O’Mari has gained visibility but remains significantly smaller than EcoCash and Innbucks.
# 6. Telecash
Parent Company: Telecel Zimbabwe
Estimated Share: Less than 1%
Telecash was once a notable player but now holds only a very small share of the market. Historical POTRAZ data showed its share declining below 1%.
# Digital Payments Beyond Mobile Money
The broader digital payments ecosystem also includes:
(Banks)
* CBZ Bank
* Steward Bank
* FBC Bank
* NMB Bank
* CABS
Infrastructure Providers
* Zimswitch
* Paynow
* Pesepay
These players facilitate card payments, internet payments, POS transactions and bank transfers throughout the economy.
# Overview
If we look at Zimbabwe’s digital payments market today:
- EcoCashremains the dominant force with roughly 70–86% market share.
- Innbucks is the fastest-growing challenger.
- OneMoney remains relevant through the NetOne ecosystem.
- Mukuru is leveraging remittances to grow wallet adoption.
- O’Mari is emerging as a financial-services-backed wallet.
- The market is gradually becoming more competitive after years of EcoCash dominance.
The biggest trend for the next five years is likely to be a gradual reduction in EcoCash’s dominance as Innbucks, Mukuru and O’Mari expand their merchant networks and digital financial services offerings.